Best online casino payment methods for Aussies: what is actually possible in 2026
 Available in US
Current as of 25 September 2026, verified against the Australian Communications and Media Authority register and the Reserve Bank of Australia’s most recent card-surcharging review.
An Australian who searches for casino payment methods is usually hoping for the same answer any other reader of this kind of page would hope for: a short, ordered list, the fastest option at the top, the slowest at the bottom, a quick note on fees. The honest answer in 2026 is shorter than that and lands harder. Offering online casino games to a person physically in Australia is prohibited under the Interactive Gambling Act 2001, and the prohibition extends to the payment side of the transaction. No state or territory licenses it. The big international casinos that show up in the search results are not licensed in Australia and never will be, because the regime does not license this product. The methods below describe what is and is not possible for someone sitting in Australia in 2026, and they describe the offshore sites that advertise to Australians anyway, because those sites are the reason the question keeps being asked.
Table of Contents
- The shape of the prohibition and why payment methods sit at the centre of it
- What the law lets an Australian use, and where it leaves them
- The ACMA record by brand and what each brand actually offers Australians
- Reading the individual brands
- What the ACMA record tells an Australian about the payment rails in practice
- How fast money actually moves on the lawful Australian rails
- Crypto, anonymity and the AUSTRAC threshold
- Responsible gambling: what works for an Australian in 2026
- Tax, winnings and the Australian Taxation Office
- The 2026 reform package
- The blocking rate, the only arithmetic that belongs on this page
- The honest shortlist for an Australian in 2026
- Frequently asked questions
The shape of the prohibition and why payment methods sit at the centre of it
Australia’s online wagering rules were drawn around two products and deliberately left a third out. Wagering on racing and sport before the event is licensable, and the Northern Territory Racing and Wagering Commission supervises fifty-two of the country’s online bookmakers under that licence, including Sportsbet, Bet365 and Ladbrokes, with the commission meeting once a month in Darwin and operating with no full-time staff. Lotteries and keno are licensable through state and territory arrangements. Online casino games, online pokies and in-play betting are not, and the Interactive Gambling Amendment Act 2017 closed off the loopholes that had let offshore operators market to Australians under thin licences. The 2023 amendments tightened that further by banning credit cards and credit-related products as a way to fund even the wagering services that are licensed.
The way the prohibition bites on a payment method is twofold. First, an Australian-licensed operator cannot accept a credit card, a credit-related product or digital currency for online wagering — that rule took effect on 11 June 2024 and carries operator penalties up to A$247,500. Second, the licensed operator must offer a way for a customer to set a deposit limit and to enter BetStop, the National Self-Exclusion Register, which has been live since August 2023. Both requirements run through the payment layer. An offshore casino is connected to neither. A player sending a deposit to an offshore site uses a payment rail that has been routed around, not a payment rail that has been regulated.
What the ACMA has actually done about the offshore sites
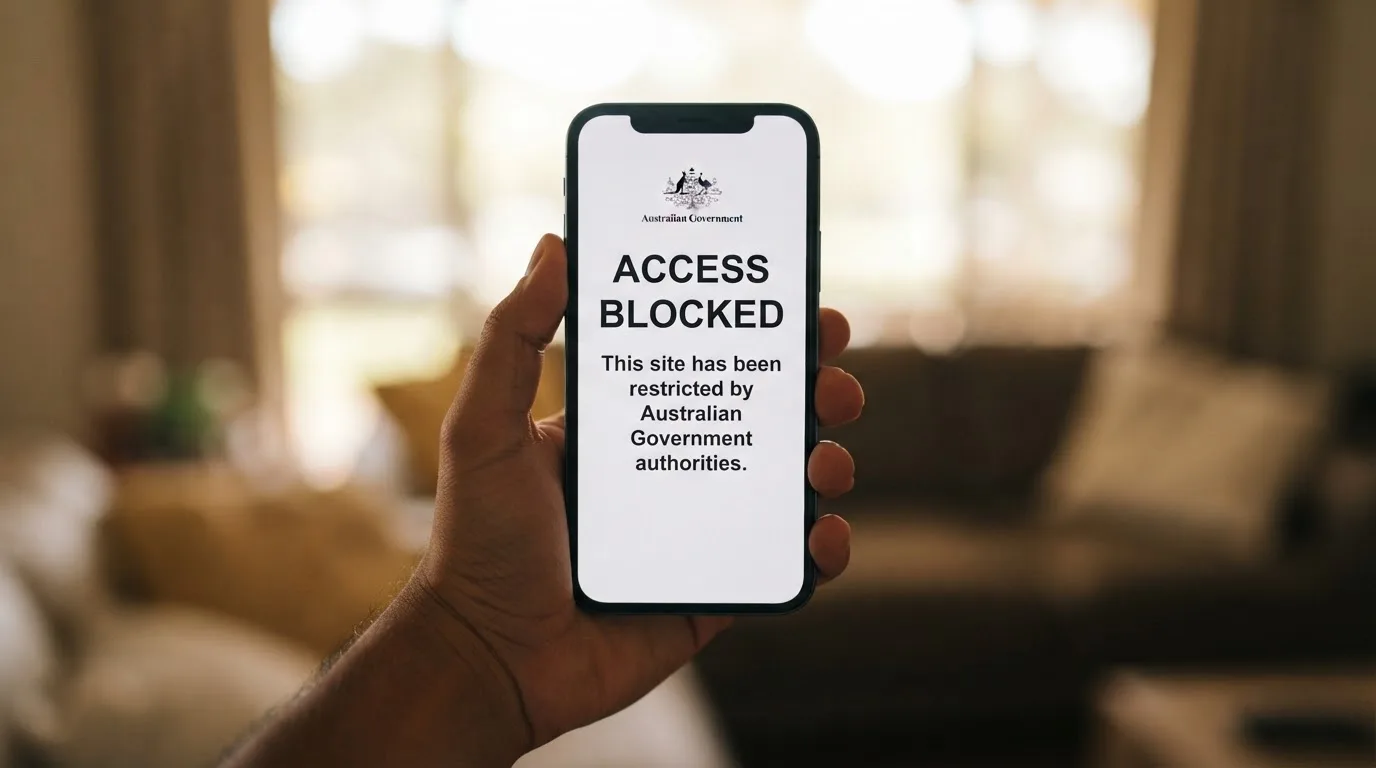
The Australian Communications and Media Authority is the body that investigates complaints, issues formal warnings and directs Australian internet service providers to block websites. As of a round reported on 26 June 2026, the ACMA had asked ISPs to block 1,751 illegal gambling and affiliate marketing websites since the first blocking request in November 2019, and more than 230 unlicensed gambling services had left the Australian market since enforcement was strengthened in 2017. A single 26 June 2026 round asked ISPs to block twelve more: 7Signs, ChromaBet, Donbet, Duospin, Freshbet, Slots Gem, Jacks Club, Lucky Start, Pointsbetz, Spinrise, Vinyl Casino and Wildsino. The pace is steady, not dramatic, and it has produced a long list rather than a few headline takedowns.
Blocking a website at the ISP level does not stop a determined player with a virtual private network, and it does not return money already on the site. What it does is remove the casual route by which most Australians would find an unlicensed site through a search engine. The combination of blocking and formal warnings is the reason most of the offshore brands that once advertised on Australian television no longer appear in mainstream Australian advertising at all.
What the law lets an Australian use, and where it leaves them
For the products that are licensed in Australia — wagering on racing and sport, lotteries, keno — the deposit rails are narrower than they used to be. A licensed online wagering service will accept a debit card, a bank transfer, PayID, Osko and BPAY. It will not accept a credit card, will not accept a credit-related buy-now-pay-later product and will not accept cryptocurrency. The credit-card ban is enforced, and the licensed operators carry the consequences if they breach it. The Australian Payments Plus operator page for Osko confirms that a transfer between participating Australian banks arrives in under a minute, twenty-four hours a day, seven days a week, addressed either to a BSB and account number or to a PayID.
For online casino games the picture is the opposite: no Australian deposit rail is lawfully usable for the product, because the product itself is not lawfully offered. The deposit rails an Australian player ends up using to fund an offshore casino are working against the regulatory design rather than within it. A bank that wants to refuse an authorisation has the merchant category code “Betting/Casino Gambling” to match against, and the major banks have used it. Westpac’s gambling block works at card level and refuses authorisation of transactions registered under that merchant category code on eligible personal credit and debit cards. ANZ’s gambling block, once activated in the ANZ app, blocks gambling transactions made through a digital wallet such as Apple Pay on an eligible card, not just the physical card; removing the block requires a 48-hour waiting period, and ANZ warns that not all gambling transactions will be blocked and that some non-gambling transactions might be blocked in error. Commonwealth Bank’s gambling lock sits in the CommBank app and operates on the same logic. Apple, for its part, charges no consumer fee for Apple Pay and does not set the transaction limits or PIN requirements — those are set by the card issuer or by the merchant.
The Reserve Bank’s July 2025 review of card payment costs proposes removing surcharges only on eftpos, Mastercard and Visa, explicitly leaving American Express outside the proposed surcharge ban. That matters at the casino cashier because the surcharge landscape is uneven across the four-card network, and Amex’s three-party structure means it issues cards and processes transactions itself, the way it has since the company’s first charge card launched on 1 October 1958. Apple Pay, Google Pay and Samsung Pay together accounted for around 45 per cent of all card payments in Australia by number at the end of 2025, which means a transaction blocked on the underlying card is blocked at the wallet too.
The cost of going outside the rails
Going outside the regulated rails does not just mean a slower payout or a small surcharge. It means stepping outside the Australian consumer protection that exists for the products the law does license. An offshore casino gives no Australian complaints body, no recourse if a withdrawal is refused, and a real chance that the site is blocked while a balance is still on it. H2 Gambling Capital’s 2025 report estimates that Australians lose about A$3.9 billion a year to illegal gambling sites and that the share of gambling going through legal channels fell from 74 per cent in 2021 to 64 per cent. The figure is an estimate, not a measurement, and it captures money that left the country and money that arrived back less than it left, which is most of it.
The ACMA record by brand and what each brand actually offers Australians
The ACMA’s formal warnings are the most useful public list of which offshore brands have been found offering prohibited services to Australians. The list is not a recommendation and the order below is not a ranking — each brand is included because the regulator has named it, and the table is meant to make that easier to scan than the ACMA’s own news pages. The columns describe the ACMA action and date, the operator entity the ACMA named, and what the publicly available listings say about the payment methods each brand surfaces on its cashier page. Where a listing does not name a payment method for this brand, the cell is left empty rather than guessed.
Brands the ACMA has formally warned
| Brand | ACMA action and date | Operator named by the ACMA | Subject support |
|---|---|---|---|
| RocketPlay | Formal warning, March 2026; earlier Dama N.V. warning, May 2022 | Pulsup Ltd (RocketPlay) | Listings describe GamblingInsider entries only |
| Level Up Casino | Formal warning, May 2022 | Dama N.V. | Listings describe Westpac references only |
| Woo Casino | Formal warning, March 2025 | Dama N.V. | — |
| Spirit Casino | Formal warning, May 2025 | Dama N.V. | — |
| National Casino | Formal warning, July 2025 | Consolutetish S.R.L. | Listings reference acma.gov.au, austrac.gov.au and betstop.gov.au |
| Bizzo Casino | Formal warning, July 2025; earlier TechSolutions warning, 2022 | Consolutetish S.R.L. | Listings describe GamblingInsider entries only |
| Ignition Casino | Formal warning, July 2025 | Bamboo Media | — |
| Instant Casino | Formal warning, February 2025 | EOD Code SRL | Listings reference EcoPayz and PayID |
| Jackbit | Formal warning, April 2026 | Ryker B.V. | — |
| Casino Intense | Formal warning, April 2025 | Sterplay Holding Ltd | Listings reference austrac.gov.au, betstop.gov.au and GamblingInsider |
| Sky Crown | Formal warning, September 2022 | Hollycorn N.V. | — |
The “Subject support” column follows what the publicly available listings say, not what the brand’s own marketing claims. Where the listings name a payment method for a brand, that is what the column records. Where the listings do not, the cell is left empty, which is the honest answer for that brand today. The column is not a quality judgement, and the order of the rows is not a ranking — a brand named in a 2026 formal warning is not “better” or “worse” than one named in a 2022 warning, it is just more recent.
Reading the individual brands
What follows is the page’s own reading of each brand, in the order the ACMA record sets. The verdicts are short and they are different — the point of writing each one is to close on what that specific brand’s record actually shows, not to repeat the same suitability line under eleven different names.
RocketPlay
Two formal warnings, the most recent of which was issued to Pulsup Ltd in March 2026 over RocketPlay, after an earlier Dama N.V. warning in May 2022. A site that has been warned twice in four years under two different operating entities is not signalling that it intends to leave the Australian market. The fact that the regulator had to issue a second warning at all is the answer to the question of whether the first one changed the operator’s behaviour.
Level Up Casino
Wamed in May 2022 as one of six Dama N.V. brands in a single ACMA round, alongside Bambet, Dazard, Rocketplay, Wild Tornado and Cobra Casinos. Level Up has not, on the public record, been the subject of a fresh formal warning since, which is consistent with the operator having de-listed from the Australian market rather than with anything else.
Woo Casino
Wamed in March 2025 over Woo Casino specifically. Dama N.V. is the operating entity. The cashier pages advertising this brand do not surface Australian-specific rails, which is consistent with a brand that is not designed for Australian deposit at all.
Spirit Casino
Wamed in May 2025, again under Dama N.V. The pairing with Woo Casino two months earlier is the ACMA’s way of saying the same operator is being warned twice within a quarter, on different brands, for the same conduct.
National Casino
Wamed in July 2025 under Consolutetish S.R.L., alongside Bizzo Casino in the same round. The operator entity is Romanian, and the brand surfaces no Australian-specific deposit rails. The ACMA warning is not a finding about the brand’s payment reliability — it is a finding that the brand is offering a prohibited product to Australians at all.
Bizzo Casino
Wamed twice: first under TechSolutions in 2022, then under Consolutetish S.R.L. in July 2025. A second warning under a different operating entity, four years later, is the ACMA telling the same conduct under a different corporate wrapper. The brand has changed the company behind it more often than it has changed the product.
Ignition Casino
Wamed in July 2025 under Bamboo Media. Ignition is one of the longer-running offshore brands in this set and has been the subject of US-state action as well, though that is a different regulatory jurisdiction with a different set of consumer protections.
Instant Casino
Wamed in February 2025 under EOD Code SRL. The brand surfaces deposit methods on its cashier that include the kind of e-wallet tokens listed on EcoPayz and the PayID infrastructure, both of which is consistent with a brand that advertises to Australians specifically even though the product itself is prohibited.
Jackbit
Wamed in April 2026 under Ryker B.V., alongside CasinOK in the same round. The brand has no Australian-licence footprint and has not, on the public record, been the subject of an earlier warning.
Casino Intense
Wamed in April 2025 under Sterplay Holding Ltd. The brand surfaces no Australian-specific deposit rails and its payment-method listings reference the regulator and the self-exclusion register rather than local rails, which is consistent with the brand’s regulatory profile rather than its product design.
Sky Crown
Wamed in September 2022 under Hollycorn N.V., alongside Blue Leo, in a formal warning the ACMA published as a PDF. No further warning has followed on the public record. Sky Crown is one of the older entries in this set.
What the ACMA record tells an Australian about the payment rails in practice
Read across the table, the ACMA record is not a list of rogue operators and a list of careful ones. It is a list of eleven offshore brands, almost all of which have been found offering prohibited services to Australians at least once, several of them twice, and none of which has an Australian licence for the product they are selling. The payment methods they surface on their cashier pages are an attempt to make the deposit frictionless for an Australian player in spite of that fact, not because of it. The “subject support” column is the page’s way of being honest about how thin the publicly available evidence for each brand’s Australian deposit story actually is.
For a reader in Australia the relevant comparison is not which of these eleven brands pays out fastest. None of them is licensed in Australia. None of them is subject to Australian consumer protection. None of them is connected to BetStop. The relevant comparison is what each one would have to do to be lawful, which is to stop offering the product to Australians at all. Until that happens, the payment method is a smaller question than the product it is funding.
How fast money actually moves on the lawful Australian rails
The lawful rails an Australian can use for the products they are allowed to play are faster than most readers expect, and faster than the offshore brands that are still accepting Australian deposits can usually match for the reverse direction. Osko, the instant transfer layer that sits on the New Payments Platform, runs transfers between participating Australian banks in under a minute, twenty-four hours a day, including weekends, addressed either to a BSB and account number or to a PayID. The New Payments Platform went live on 13 February 2018, and is owned by New Payments Platform Australia Ltd, a non-profit whose thirteen shareholders include the Reserve Bank of Australia and the country’s major banks. By April 2025, more than 25 million PayID identifiers had been registered on the platform. Participants must keep the platform’s monthly outages to no more than two minutes.
PayID carries a feature Osko and ordinary BSB-and-account transfers do not: paying to a PayID shows the name of the account holder before the transfer is sent. Australian Payments Plus warns that being asked to transfer money to a PayID on an illegal gambling site almost certainly means a scam site. That single safeguard — the account-holder name on the confirmation screen — is the most consequential payment-method feature a person sitting in Australia can use, because it is the one that tells the punter what the cashier page does not. PayID-based instant transfers are available at over 100 Australian financial institutions.
BPAY is the bill-payment rail in Australian online banking and has been operating since 18 November 1997; it is available in the online banking of over 140 banks and financial institutions and is offered by over 95,000 businesses. It runs through Australian Payments Plus, the same operator that runs PayID and Osko, and it is owned equally by ANZ, Commonwealth Bank, National Australia Bank and Westpac via Cardlink Services Limited. BPAY was the first instant bill-payment rail Australian consumers used and is the one most likely to be offered by a licensed wagering operator’s deposit page. Its limitation is that it was designed for bills, so the deposit takes the form of a payment to a biller code and a customer reference number rather than a transfer to a BSB and account number.
Where speed matters and where it does not
For a deposit to a licensed Australian wagering service, Osko and PayID clear in under a minute. BPAY clears on the same business day in most cases and is the right rail for a deposit the punter does not need to be settled instantly. A debit card routed through Visa or Mastercard clears at the speed of the card network, which is near-instant at the cashier, with settlement to the operator following on the bank’s own timeline.
For a withdrawal, the direction that matters to the punter, the rail is determined by the operator rather than by the punter. A licensed Australian wagering operator will pay back to a bank account via Osko or to a PayID; an offshore casino will pay by the method the punter chose on deposit, subject to the operator’s own processing window, which is the part that varies and is the part the punter cannot speed up from their end.
Crypto, anonymity and the AUSTRAC threshold
Cryptocurrency is treated differently in the lawful and unlawful parts of the market. Under the 2023 amendments to the Interactive Gambling Act 2001 and the rules that took effect on 11 June 2024, Australian-licensed online wagering services cannot accept digital currency as a deposit. The credit-card ban applies to credit-related products and to linked digital wallets such as Apple Pay, where the underlying funding instrument is a credit card. Cryptocurrency is not on the licensed wagering side at all.
For an Australian punter funding an offshore casino, cryptocurrency is one of the deposit methods the offshore cashier will usually offer. It is described in marketing as anonymous. The reality is closer to pseudonymous: every transaction is recorded on the blockchain and is traceable from one end to the other with standard chain-analysis tools, and the on-ramp and off-ramp at the Australian dollar end is a regulated entity. AUSTRAC’s threshold-transaction-report rule, which requires reporting of transfers of A$10,000 or more, applies only to physical cash; ordinary electronic bank transfers are not subject to that per-transaction reporting requirement, regardless of the amount sent. The A$10,000 figure is not a privacy threshold for bank transfers or for crypto on-ramps, because the rule is not the one that does the reporting. The exchanges that convert Australian dollars to cryptocurrency do their own customer identification and keep their own records, and those records can be obtained by AUSTRAC on request.
For a punter, the practical question is not whether a cryptocurrency deposit is untraceable. It is whether the deposit routes the punter around an Australian consumer-protection regime they would otherwise have, and the answer is yes — the protection is not transferable across the cryptocurrency rail because the protection does not exist for the product on the receiving side.
Responsible gambling: what works for an Australian in 2026
The Australian-licensed side of the market has a set of responsible-gambling tools that the offshore side does not. BetStop, the National Self-Exclusion Register, has been live since August 2023 and binds every Australian-licensed online and phone wagering service. A punter who registers with BetStop cannot open a new account with any Australian-licensed online or phone wagering operator for the period of their exclusion, and the operator is required to close the punter’s existing accounts. The exclusion periods range from three months to a permanent exclusion.
The offshore casinos in the ACMA’s record are not connected to BetStop, because they are not Australian-licensed services. The bank-side blocks — Westpac’s gambling block, ANZ’s gambling block with its 48-hour waiting period for removal, Commonwealth Bank’s gambling lock in the CommBank app — are an Australian punter’s most effective second line of defence. Each operates at the merchant-category-code level: the bank refuses authorisation of a transaction coded as “Betting/Casino Gambling” on the underlying card, and on linked digital wallets such as Apple Pay where the wallet is funded by the blocked card. ANZ’s warning that not all gambling transactions will be blocked and that some non-gambling transactions might be blocked in error is honest about the limits of merchant-category-code blocking: it works on the code, not on the content, and the code is set by the merchant, not by the bank.
The National Gambling Helpline, 1800 858 858, is free, runs 24/7 and offers chat through Gambling Help Online. The helpline and the chat service are the right first call for a punter who is worried about their own play or about someone else’s.
Tax, winnings and the Australian Taxation Office
Recreational gambling winnings are not assessable income in Australia under section 6-5 of the Income Tax Assessment Act 1997, and losses are not deductible. The ATO’s position is that the punter is not carrying on a business of gambling unless they meet the criteria for a business, which is a separate question. The practical reading for a punter is that a payout from an offshore casino is not taxable in Australia and a loss from the same casino is not refundable against other income. The offshore operator may withhold at source in its own jurisdiction, and that is a separate question, settled under that operator’s own tax rules rather than the ATO’s.
The 2026 reform package
The Interactive Gambling Amendment (Gambling Reform) Bill 2026 passed Parliament on 19 August 2026. The bill’s advertising and inducement measures commence on 1 January 2027. On a 2026 page the bill is law with a start date, not law in force, and a reader who is seeing a marketing message in 2026 is seeing one that was lawful when it was published and that the reform package will tighten from the start of 2027. The bill is not a reopening of the prohibition on online casino games; it is a tightening of the rules around licensed wagering.
The blocking rate, the only arithmetic that belongs on this page
The page’s only prescribed arithmetic is the blocking rate: the running total of blocked sites divided by the time elapsed since the first blocking request. As of the round reported on 26 June 2026, the ACMA had asked ISPs to block 1,751 illegal gambling and affiliate marketing websites since the first blocking request in November 2019. That is roughly 80 months from November 2019 to June 2026, which puts the blocking rate somewhere between 21 and 22 sites per month over the full period, with the rate higher in the months immediately after a round and lower in the months between rounds. The honest reading is that the ACMA does not block at a constant rate and a single month’s numbers should not be read as the trend. The trend is steady: more than two hundred unlicensed services have left the Australian market entirely since 2017, and the blocking programme continues to operate on roughly the same monthly cadence it has run on since 2019. The arithmetic is the page’s only number, and the only honest reading of it is a band rather than a single figure.
The honest shortlist for an Australian in 2026
A reader who came to this page looking for the best online casino payment method is owed a direct answer, not a recommendation to use one of the offshore brands the ACMA has warned. The direct answer is that the best online casino payment method for an Australian in 2026 is to not make the payment at all, because the product on the receiving side is prohibited and the protections a licensed Australian wagering service offers are not transferable to an offshore casino. A deposit rail is only as good as the product it is funding, and the product on the offshore side of the table is the one the ACMA has been warning these operators about since 2017.
For the products the law does license — wagering on racing and sport, lotteries and keno — the payment method is straightforward: a debit card, a bank transfer, a PayID, an Osko instant transfer or a BPAY payment, used through an Australian-licensed operator that is connected to BetStop and to the bank-side gambling blocks. The speed is real — under a minute on Osko — and the consumer protection is real, because it is enforceable in Australia.
For a punter who has decided to play anyway, the offshore brand is not the relevant question. The relevant questions are: which of the bank-side blocks is on, whether the card being used is a debit card or a credit card, and whether the A$ figure being sent is one the punter can afford to lose with no Australian recourse if the operator refuses the withdrawal. The ACMA’s blocking record is the answer to whether a site is still reachable through a normal Australian internet connection on any given day; it is not, and has never been, a guarantee that the balance is recoverable.
The page’s verdict is the same as the regulator’s, framed in the language of payment methods rather than the language of consumer protection: there is no best online casino payment method for Australians in 2026 for the product most of these brands are selling, because the product is prohibited and a payment rail cannot make it lawful. The payment rail that does work — for the products the law does license — is the same one that has worked for a decade: PayID, Osko, BPAY and a debit card, used through an Australian-licensed operator that is connected to BetStop and is subject to Australian consumer law.
Frequently asked questions
What payment methods are commonly advertised by online casinos targeting Australians?
Offshore casinos targeting Australians typically advertise credit and debit cards, a handful of e-wallets, bank transfers and cryptocurrency on their cashier pages. None of those methods makes the underlying product lawful in Australia, and an Australian bank may refuse a transaction coded as “Betting/Casino Gambling” regardless of the method used at the cashier.
How does an Osko transfer compare with a card payment for speed?
Osko transfers between participating Australian banks arrive in under a minute, twenty-four hours a day, including weekends, addressed either to a BSB and account number or to a PayID. A card payment clears near-instantly at the cashier, with settlement to the operator following on the bank’s own timeline, and the merchant-category-code block sits in front of either rail.
Is it legal for an online casino to process payments from players in Australia?
No. Under the Interactive Gambling Act 2001 as amended, it is an offence to provide online casino games to a person in Australia, and the credit-card ban for licensed wagering has been in force since 11 June 2024. The offshore casino, not the punter, is the party the regulator prosecutes, but a punter using an offshore casino has no Australian consumer protection.
Are cryptocurrency payments harder to trace than a bank transfer?
Cryptocurrency transactions are recorded on a public ledger and are traceable with standard chain-analysis tools; the Australian-dollar on-ramp and off-ramp are regulated entities that keep their own records. AUSTRAC’s A$10,000 threshold-transaction-report rule applies to physical cash, not to bank transfers or to cryptocurrency, and the absence of that rule is not the same as the absence of reporting.
What makes a casino payment method secure rather than just fast?
Security for an Australian punter runs through three layers: an Australian-licensed operator that is connected to BetStop and to the bank-side gambling blocks, a payment rail that the operator’s own regulator recognises (debit card, bank transfer, PayID, Osko, BPAY), and a bank that has the gambling block turned on. A fast deposit to an offshore casino is none of those three things and is not made safer by being faster.
Does PayID offer any extra protection compared with a BSB and account number?
Yes. Paying to a PayID shows the name of the account holder before the transfer is sent, and Australian Payments Plus warns that being asked to transfer money to a PayID on an illegal gambling site almost certainly means a scam site. PayID-based instant transfers are available at over 100 Australian financial institutions, and the New Payments Platform went live on 13 February 2018.
Published by the Casino Live Dealer Hub team.